What is the cash conversion cycle?
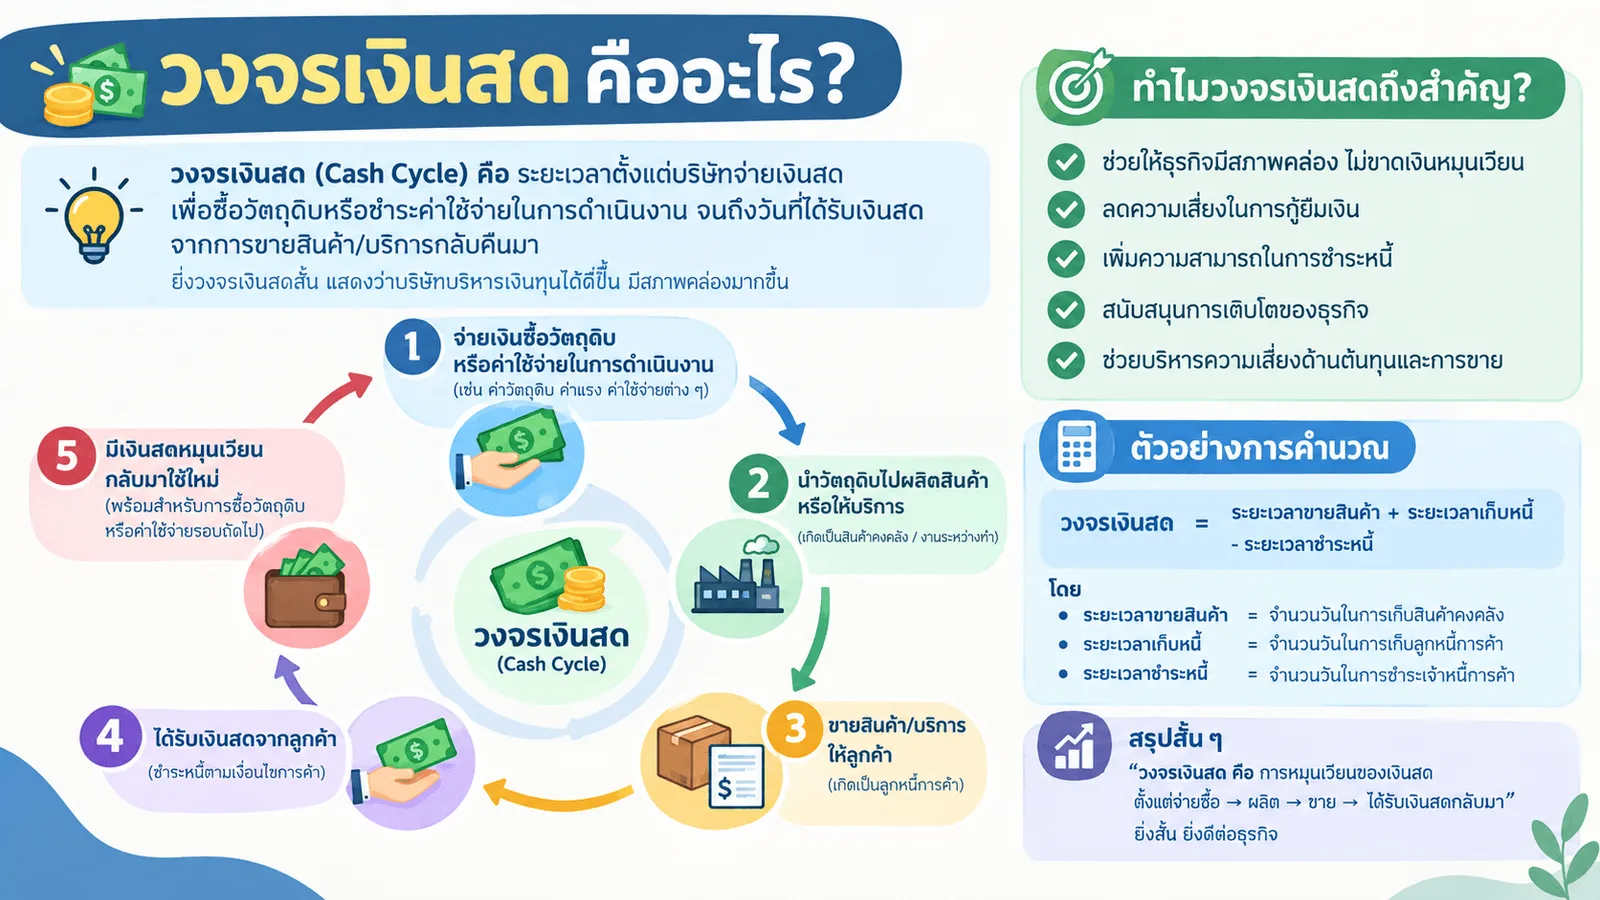
Why does a profitable business run out of cash? Unlocking the secret of the 'Cash Conversion Cycle'—the critical factor that determines whether a business survives or fails.
The Cash Conversion Cycle (CCC) is the average time span between the day a business pays cash for goods or raw materials and the day it receives cash back from customer payments. It is a vital tool for assessing a company’s liquidity and the efficiency with which it manages its working capital.
Key Components of the Cash Conversion Cycle
The Cash Conversion Cycle consists of three main variables:
Days Inventory Outstanding (DIO)
Definition: The average number of days inventory remains in stock before being sold. A lower value is better, as it indicates that the company can move its inventory quickly.
Calculation Formula: (Average Inventory ÷ Cost of Goods Sold) × 365
Days Sales Outstanding (DSO)
Definition: The average time taken to collect cash from accounts receivable (in cases where goods are sold on credit—i.e., delivering goods before receiving payment). A lower value is better, as it allows the company to receive cash sooner.
Calculation Formula: (Average Accounts Receivable ÷ Total Sales) × 365
Days Payable Outstanding (DPO)
Definition: The average time a company takes to pay its trade creditors. A higher value is generally better, as it allows the company to retain cash for a longer period and may reflect strong credibility with suppliers.
Calculation Formula: (Average Accounts Payable ÷ Credit Purchases) × 365
(If the figure for credit purchases is unavailable...) (Cost of goods sold may be used as an alternative.)
Cash Conversion Cycle Formula
Cash Conversion Cycle = Days Inventory Outstanding (DIO) + Days Sales Outstanding (DSO) – Days Payable Outstanding (DPO)
Cash Conversion Cycle Calculation Example
ABC Co., Ltd., an online fashion clothing retailer, has the following data from its financial statements:
Average Inventory: 600,000 THB
Average Accounts Receivable: 500,000 THB
Average Accounts Payable: 400,000 THB
Cost of Goods Sold (annual): 3,700,000 THB
Revenue (annual): 6,450,000 THB
Calculation Method:
Days Inventory Outstanding (DIO) = (600,000 ÷ 3,700,000) × 365 = 59 days
Days Sales Outstanding (DSO) = (500,000 ÷ 6,450,000) × 365 = 28 days
Days Payable Outstanding (DPO) = (400,000 ÷ 3,700,000) × 365 = 39 days
Cash Conversion Cycle Calculation:
Cash Conversion Cycle = 59 + 28 – 39 = 48 days
Conclusion: ABC Co., Ltd. must set aside working capital to support its operations for 48 days—the period spanning from the day it pays for inventory to the day it receives payment from customers.
What does the Cash Conversion Cycle indicate?
The Cash Conversion Cycle reflects a company's level of financial liquidity. This can be categorized into three main scenarios:
Positive Cash Conversion Cycle: The business pays for inventory but must wait several days before receiving cash from customers. A higher positive figure indicates a greater risk of a potential cash shortage.
Zero Cash Conversion Cycle: The business receives cash from customers on the exact same day it is required to pay its own creditors, representing a balanced cash flow.
Negative Cash Conversion Cycle: The business receives cash from customers before it is required to pay its creditors. This is the most favorable scenario, as it signifies a very high level of liquidity.
Strategies to Shorten the Cash Conversion Cycle
Reduce Days Inventory Outstanding (DIO): Move inventory as quickly as possible—for example, by running sales promotions or utilizing a First-In, First-Out (FIFO) inventory management system to prevent stock from remaining unsold for too long.
Reduce Days Sales Outstanding (DSO): Accelerate the collection of payments from customers by avoiding excessively long credit terms; for instance, offer special discounts for cash payments or early settlements.
Extend Days Payable Outstanding (DPO): Negotiate longer credit terms with suppliers, provided the business maintains a strong financial reputation.
Conclusion
The cash conversion cycle is a vital tool for assessing a company’s liquidity and working capital management. It measures the time elapsed from the moment a business pays for inventory until the moment it collects payment from its customers. A shorter—or even negative—cash conversion cycle indicates that a business has a rapid cash flow and a high degree of liquidity.