Accounting Cycle
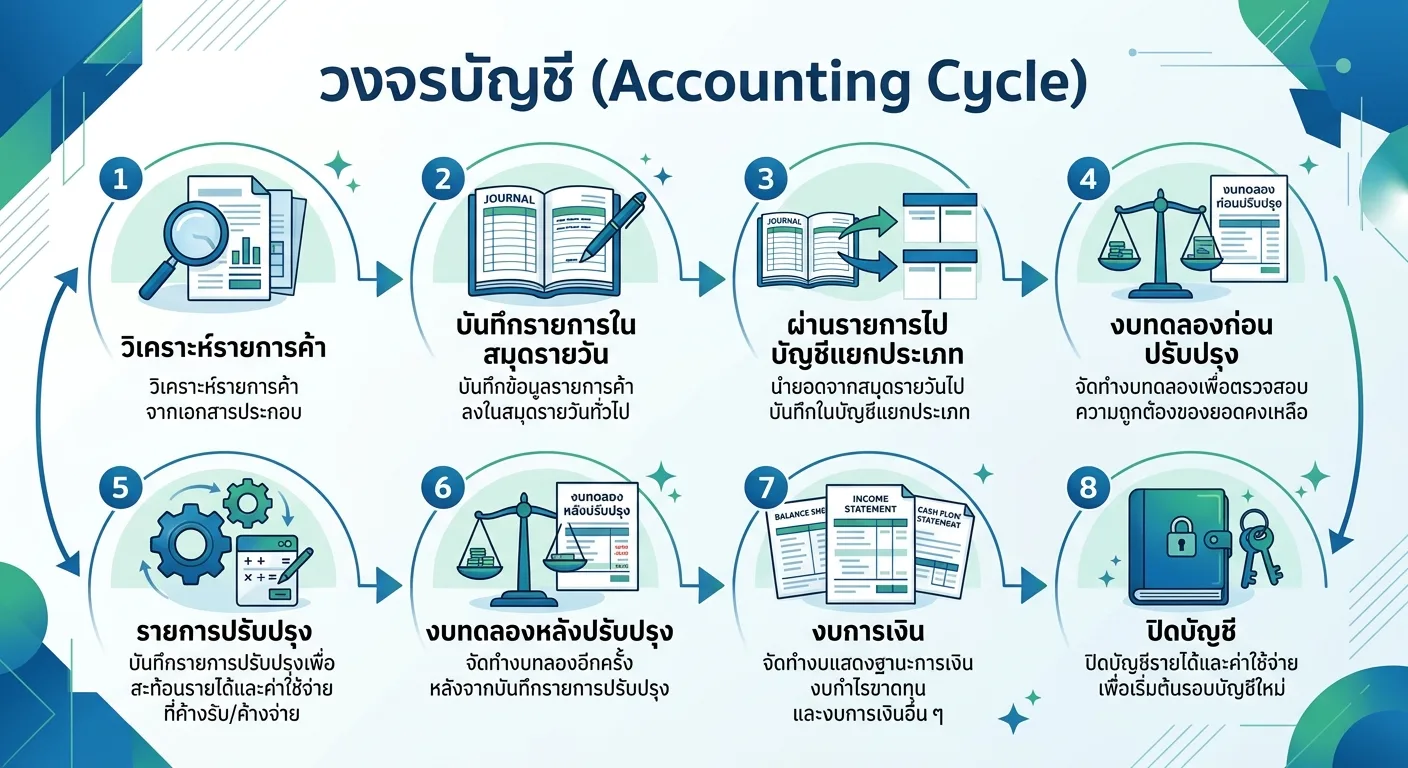
From the First Transaction to Year-End Financial Statements: Deciphering the 9 Steps of the Accounting Cycle That Every Professional Must Master
The accounting cycle is the complete process used to record transactions and prepare financial reports for a business over a specific period (typically monthly or annually), ensuring that financial information is accurate, complete, and verifiable.
Steps of the Accounting Cycle:
1. Transaction Analysis
Determine which accounts are affected by a given event.
Examine supporting documentation, such as receipts and invoices.
2. Journal Entry
Record transactions using the double-entry system (debit = credit).
Enter transactions chronologically in the general journal.
3. Posting to the Ledger
Transfer data from the journal to the general ledger.
Use this to consolidate the balances for each account.
4. Unadjusted Trial Balance
Compile balances from the general ledger to verify accuracy (debit = credit).
5. Adjusting Entries
Make adjustments for incomplete items, such as accrued expenses or accrued revenue.
Ensure compliance with the accrual basis of accounting.
6. Adjusted Trial Balance
Verify the totals once again following the adjustments.
7. Financial Statements
Income Statement
Statement of Financial Position (Balance Sheet)
Statement of Cash Flows
Statement of Changes in Equity
8. Closing Entries
Close revenue and expense accounts to the capital (equity) account.
Prepare for the start of a new accounting period.
9. Post-Closing Trial Balance (Post-Closing Trial Balance)
Verify the accuracy of the balances in permanent accounts, such as assets, liabilities, and equity.
Benefits of understanding the accounting cycle:
It makes the accounting process systematic and easy to audit.
It helps in preparing for examinations or actual professional practice.
It facilitates clear communication and a shared understanding with auditors or management.